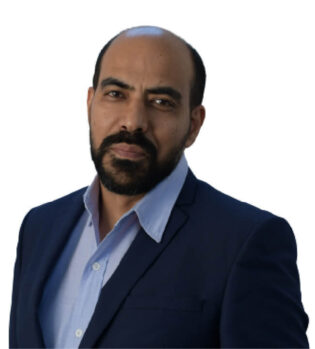
 Zubin Muriya is a seasoned Governance, Risk, and Compliance (GRC) professional with over two decades of cross-jurisdictional experience in banking regulatory compliance, financial crime risk management, corporate governance framework, and audit advisory. His work across India and the GCC (UAE, Qatar, Bahrain) reflects a career rooted in regulatory rigor and operational integrity.
As the GRC Advisory Head at VelthRad Consultants, Zubin leads the firm's compliance, risk management, and internal controls advisory functions for DIFC and ADGM based financial entities. In addition to advisory support, he also provides outsourced Compliance Officer, Money Laundering Reporting Officer (MLRO) and Risk Officer services to regulated firms. He brings extensive regulatory insight and hands-on expertise in managing approval processes, drafting robust compliance frameworks, and overseeing governance setups for newly established and growing financial institutions.
Zubin’s prior leadership roles include Executive Director - Compliance, AML & Risk at Julius Baer in Qatar and the UAE, where he was instrumental in establishing the Qatar entity and acted as an approved person with QFCRA. Earlier, he served as Director Compliance & AML at Bank J. Safra Sarasin, overseeing regional regulatory engagements in DIFC and QFC. His foundational years at Union National Bank and BMI Bank sharpened his skills in regulatory liaison, AML framework development, and operational controls.
A Chartered Accountant by qualification, Zubin also holds multiple international professional certifications including CAMS (USA), an ICA Postgraduate Diploma in GRC (UK) & Diploma in International Compliance, and a Sanctions Certification from ACAMS. He is an experienced compliance professional under the DFSA and QFCRA regimes. Additionally, he contributed to industry development as an examiner with the ICA-UK.